

Greenlight: For Families
Greenlight Financial Technology, Inc.
- Ratings
- 4.7
- Installs
- 1,000,000+
- Category
- Finance
Greenlight: For Families analysis by Appwee
I found Greenlight: For Families most useful when I stopped thinking of it as simply a children’s debit card and started treating it as a shared money-learning routine. The app gives parents a way to manage a young person’s spending while giving that child a more direct role in everyday financial decisions. That balance is the reason I would recommend it to families who want more structure than handing over cash, but more independence than approving every purchase themselves.
It is a free finance app from Greenlight Financial Technology, Inc., designed for families with children and teenagers. The service is aimed at Everyone, and its central idea is easy to understand: parents manage the experience through the app while the child uses the associated debit card. In my experience, the value is less about the card itself and more about the conversations and habits that the app can make visible.
The app has been available since late 2016 and has grown into a familiar choice in this space, with a 4.7 average from around 85 thousand ratings and over a million installs. It is currently listed as version 8.6.0 for operating systems version 10 or later. Those figures do not replace personal testing, but they do suggest that Greenlight has had time to refine a product built around a very specific family problem.
Why the parent-and-child setup works
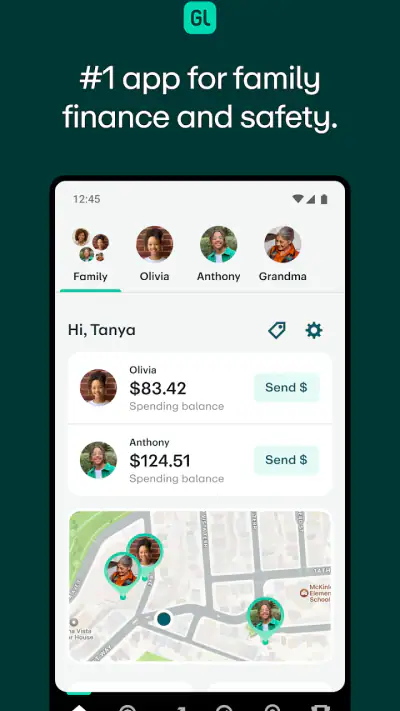
The strongest part of Greenlight is the separation of responsibilities. A parent remains the person setting the boundaries, while the child gets a more concrete experience of receiving, holding and spending money. That is more instructive than occasional cash because the child can see a running balance and make choices that have visible consequences.
I especially like this arrangement for families trying to move beyond vague instructions such as “save more” or “don’t spend everything.” A parent can use the app as a prompt for a short weekly check-in: What came in? What was spent? What is being saved for? The technology does not teach those lessons automatically, but it gives both sides something specific to discuss.
A realistic example would be a teenager preparing for a school outing. Instead of asking for money at the last minute, the teenager can look at the available balance, decide what can reasonably be spent and understand that choosing one purchase may affect another. The parent can stay involved without standing beside the checkout screen. That small shift is where the app feels more useful than a traditional allowance envelope.
The parent-controlled design also addresses a common worry: giving a young person spending access without giving up all oversight. I found the appeal strongest for parents who want to encourage independence gradually. The child gets practice, but the family still has a central place to review the arrangement and adjust expectations.
Turning allowances into a repeatable routine
One of the less obvious strengths is that Greenlight can help make allowance discussions more consistent. Families often intend to teach money skills but only talk about them after a problem. A dedicated finance app creates a natural moment to review spending before a small mistake becomes a larger argument.
My advice is to agree on the purpose of the money before using the app heavily. Is it for discretionary spending, planned needs, saving goals or a mixture? If the parent changes the rules from week to week, the child may experience the app as surveillance rather than guidance. If the rules are clear, the same screen becomes a practical lesson in planning.
This is also where the app can be more useful than cash. Cash can be simple for younger children, but it disappears quickly and leaves little record to discuss. Greenlight gives the family a shared reference point. That does not mean every transaction needs parental commentary; in fact, constant commentary would undermine the independence the product is meant to build.
For younger users, I would keep the first stage deliberately narrow. Start with a small number of spending decisions and explain what the child is responsible for. For older teenagers, the conversation can move toward prioritizing, delaying purchases and preparing for expenses that happen irregularly. The app works best when the parent changes the level of guidance as the child becomes more capable.
Where the app is stronger than ordinary alternatives
Compared with cash, Greenlight offers more visibility and a clearer bridge between parental support and a child’s own decisions. Compared with a standard bank account managed almost entirely by an adult, it puts the child’s daily spending experience closer to the center. That middle ground is its clearest advantage.
A basic banking solution may be preferable for an older teenager who already understands budgeting and needs a more conventional financial relationship. Cash may still be better for a very young child who is learning the physical idea of exchanging money. Greenlight is most convincing in the transition between those stages, when a child needs practice but is not ready for complete financial autonomy.
I also think the app suits parents who dislike being the family’s human ledger. Without a shared system, one parent may remember what was promised while the child remembers only what was requested. A central app can reduce that confusion, provided both parents use the same expectations. It is not a substitute for communication, but it can reduce avoidable misunderstandings.
The developer’s focus on families is apparent in the overall positioning, and that focus matters. This is not a general-purpose budgeting tool that happens to be usable by a teenager. Its value comes from the relationship between the adult account manager and the young card user. If that relationship is not part of your goal, much of the reason to choose it disappears.
The friction parents should consider first
The biggest limitation is that Greenlight can make money management look easier than it really is. A balance and transaction history are helpful, but financial maturity still depends on the child understanding trade-offs. A child can use the card correctly while learning very little if the parent treats the app only as a control panel.
There is also a risk of over-monitoring. Parents may be tempted to inspect every purchase and question every small decision. That can create conflict, especially with teenagers who are ready for more privacy. I would set review times in advance rather than turning each notification or transaction into an immediate conversation. The app supports oversight, but families still need to decide what reasonable oversight looks like.
Another point of friction is setup discipline. The product is not something I would hand to a child with a quick explanation and then forget. The family needs to decide how spending expectations work, what happens when money runs out and whether certain purchases require a conversation. Those decisions are not difficult, but they take time. Parents looking for a completely hands-off allowance tool may be disappointed.
The free price is attractive for trying the app, but I would still read the current service terms carefully before making it part of a long-term family routine. Financial products can involve conditions around the card or account experience, and a family should understand those details rather than choosing solely because the app itself can be downloaded without an upfront charge.
Device compatibility is another practical checkpoint. The current release requires operating system version 10 or later, so families using older phones should check compatibility before planning around it. That is a small issue for many households, but it can become frustrating when the parent’s device is the one that cannot run the app reliably.
What happens when a child makes a poor choice?
This is where I think parents should decide their policy before the first mistake. If a child spends money impulsively, removing access immediately may stop the behavior but teach little. A better response may be to review what happened, identify the trade-off and agree on a smaller next step. Greenlight can make that discussion concrete because the spending is easier to examine than a vague memory of cash being gone.
At the same time, not every family will want the same level of intervention. A younger child may need tighter boundaries, while an older teenager may benefit from being allowed to experience a manageable consequence. The app does not remove that judgment from the parent. In my view, that is both a strength and a limitation: it leaves room for thoughtful parenting, but it cannot provide the parenting strategy for you.
I would also avoid using the app as a reward-and-punishment system for every household chore. Linking money to responsibilities can work for some families, but it can also make ordinary cooperation feel purely transactional. If parents choose that approach, they should explain the arrangement clearly and keep it separate from the child’s basic sense of security. The app is a tool for organizing money, not a replacement for a family’s values.
Who will get the most from it?
Greenlight is a strong fit for parents who want to introduce a debit card while keeping a visible role in the process. It is particularly suitable when a child is beginning to ask for more independence, make small purchases without an adult and learn that money is finite. The app gives those moments enough structure to become useful practice.
It may also suit separated or busy households that need a consistent way to discuss a child’s spending responsibilities. A shared routine can be easier than passing notes, remembering verbal agreements or relying on whichever adult happens to be present. The benefit depends on adults agreeing about the rules, but the app can give those rules a common home.
I would be more cautious about recommending it to families who already have a simple, trusted system that works well. If cash allowance teaches the child what you want them to learn and the parent does not need additional oversight, adding a finance app could create unnecessary complexity. Likewise, a financially confident older teenager may prefer a conventional banking arrangement rather than a product centered on parental management.
It is not the best choice for someone seeking a personal budgeting app for their own finances. The product’s identity is family-centered, and its usefulness comes from managing a young person’s card experience. Adults looking only for expense tracking, bill planning or independent account management should compare it with tools designed specifically for those tasks.
Practical ways to use it without creating arguments
I would begin with one clear purpose, such as managing discretionary spending, rather than trying to teach every financial lesson at once. Explain what the child can decide alone and what deserves a conversation. Then schedule a brief review after the child has had enough time to make real choices. This keeps the app connected to learning instead of making it feel like a daily inspection.
A useful exercise is to ask the child to predict how long the balance should last before spending begins. Later, compare the prediction with what actually happened. That turns the app into a feedback loop and teaches planning without requiring a formal budgeting lecture. It also reveals whether the allowance or spending arrangement matches the child’s real needs.
For teenagers, I would use the app to discuss delayed purchases. When something appealing comes up, ask whether buying it now changes the ability to pay for a planned activity later. The point is not to reject every spontaneous purchase; it is to make the trade-off visible. That is a more realistic lesson than demanding perfect saving.
Parents should also agree on what counts as a private purchase. A teenager may accept financial guidance more readily if not every small transaction becomes a family debate. Set boundaries around safety and responsibility, then allow room for ordinary judgment. This is one of the most important trade-offs in a parent-managed card: visibility can build trust, but excessive scrutiny can damage it.
My final view of Greenlight
After looking at how the product fits everyday family life, I see Greenlight as a practical bridge between cash allowance and independent banking. Its best quality is not that it makes spending effortless; it is that it gives parents and children a shared structure for discussing spending, saving and responsibility. The card is the visible part, but the learning routine is the real product.
I would recommend it to families ready to stay involved without handling every purchase personally. It is especially compelling when a child is asking for more freedom and the parent wants a gradual, observable way to provide it. The 4.7 average and broad adoption show that many families find the approach appealing, but the right fit still depends on how much guidance your household wants.
I would skip it if you want a totally passive allowance system, if your child is too young to understand the choices involved or if an older teenager already needs a more independent banking setup. I would also avoid adopting it without first discussing privacy, spending limits and what happens after a mistake.
For the right family, Greenlight turns ordinary purchases into manageable financial practice. It does not guarantee responsible behavior, and it cannot replace a parent’s judgment, but it can make money conversations clearer and more regular. That makes it a worthwhile finance app for families who want independence to grow gradually rather than arrive all at once.
Gallery
Greenlight: For Families Pros and Cons
- Parents can manage multiple children from one family account.
- Custom card controls help limit where and how kids spend money.
- Real-time purchase notifications improve visibility over spending.
- Educational money tools encourage conversations about saving and budgeting.
- The interface is generally simple for children to navigate independently.
- Availability and features may vary depending on the family’s location.
- Some useful controls may require a paid Greenlight subscription.
- Children need a compatible smartphone for several app-based features.
- Cash deposits and withdrawals may not be as convenient as bank transfers.
- Account setup can require identity and parental verification details.
Greenlight: For Families Frequently Asked Questions
What is Greenlight: For Families?
Greenlight: For Families is a family-focused money management app designed to help parents teach children about spending, saving, earning, and responsible financial decisions. Parents generally manage the account, set controls, and monitor activity, while children can use an associated card or app features according to the plan and permissions selected by the family.
How does the Greenlight card work for children?
The Greenlight card is a parent-controlled payment card intended for a child’s everyday purchases. Parents can typically decide where and how the card may be used, review transactions, receive notifications, and add money when needed. Availability, card features, spending limits, and merchant restrictions can vary depending on the subscription plan and the child’s age.
How much does Greenlight: For Families cost?
Greenlight: For Families is generally offered through a recurring subscription rather than as a completely free service. Pricing may differ according to the selected plan, billing frequency, promotions, and optional features such as investing or enhanced protection. Before signing up, review the current pricing page carefully, including trial terms, renewal conditions, and any additional charges.
Is Greenlight: For Families safe and suitable for children?
The app is built around parental supervision, with tools intended to help adults control spending and discuss financial habits with their children. Parents should still review permissions, privacy settings, notifications, and account activity regularly. Greenlight is not a replacement for parental guidance, and families should confirm that the service’s age requirements and features suit their children.
What do parents need to sign up for Greenlight: For Families?
A parent or legal guardian normally needs to create the primary account, provide personal and payment information, and complete any identity or eligibility checks requested during registration. The child’s details may also be required to create a supervised profile. Requirements can change by country and product version, so check the official terms before downloading or submitting sensitive information.














